Forex Broke reviews are hard to trust when they mix affiliate hype, angry forum threads and star ratings you cannot check. This guide answers one question: is Forex.com safe and legit? It also gives you a method you can apply to any broker before you deposit a dollar.
📑 Table of Contents
- Why Forex Broke Checks Matter Before You Deposit
- What a Useful Review Includes
- Is Forex.com Safe? Regulation and Ownership Explained
- How to Vet a Forex Broke Step by Step
- Forex.com Fees, Spreads and Account Types
- Platforms, Tools and Education
- What Real Users Say About Forex.com
- How to Spot Fake Reviews and Forex Broke Red Flags
- Who Forex.com Suits and How to Test It With Low Risk
- Conclusion: Is Forex.com Legit?
- FAQ
The short answer is yes, with conditions. Forex.com is run by StoneX, a Nasdaq-listed group, and its U.S. entity is registered with the CFTC and is an NFA member. Users mostly complain about spreads, inactivity fees and slow support, not about lost funds.
Why Forex Broke Checks Matter Before You Deposit
Retail forex carries two separate risks. Market risk is the chance your trade loses money. Counterparty risk is the chance your broker misprices trades, blocks withdrawals or disappears. Reviews are the cheapest way to measure the second risk before it costs you anything.
Your broker holds your money
When you deposit, you hand funds to a company you will probably never speak to. A U.S.-regulated broker must keep client money separate from its own and meet minimum capital rules. An unregulated offshore broker has no such duty, and the two can look identical on a website until you try to withdraw.
Bonuses add fine print
A $30 no-deposit credit sounds free, but the terms may require a minimum trading volume, cap your profits or void the bonus after one rule slip. Read reviews and the bonus terms together before you claim anything.
What a Useful Review Includes
A good review gives you facts you can verify. A weak one gives you adjectives. Look for these items:
- The regulator and license number, so you can confirm them on the regulator’s own register
- The legal entity that holds your account
- The full fee picture: spreads, commissions, inactivity fees and withdrawal fees
- Withdrawal speed, with documented disputes if any exist
- The review date and the account type that was tested
The entity point trips up many traders. A broker group can be regulated in one country while the company serving your country is not. Your protection depends on the entity you sign with, not on the brand name on the homepage.
A broker’s brand tells you nothing about your protection. The regulated entity on your account agreement does.
Is Forex.com Safe? Regulation and Ownership Explained
Who owns Forex.com
Forex.com is a brand of StoneX Group Inc., a Nasdaq-listed financial services firm. Public ownership means audited financials and regulatory filings, which many offshore brokers never publish. That is a strong sign the company is not a fly-by-night operation.
Ownership is not protection, though. Your deposit is only as safe as the regulated entity that holds it, and corporate groups often rename or restructure subsidiaries. Confirm the exact company name on your account agreement before you check any register.
Regulation by region
The brand operates under separate licenses depending on where you live. Verify the current entity name on each regulator’s own site, since filings change over time.
| Region | Regulator | What it means for you |
|---|---|---|
| United States | CFTC and NFA | Registered retail forex dealer, NFA member, capital and reporting rules |
| United Kingdom | FCA | Authorized firm, FSCS compensation scheme may apply |
| Canada | CIRO | Self-regulatory oversight, investor protection rules |
| Australia | ASIC | Licensed provider, dispute resolution access |
U.S. rules are among the strictest in the industry. Retail forex dealers must hold a minimum of $20 million in net capital, and leverage on major pairs is capped at 50:1. Forex.com also follows the NFA’s FIFO rule, which means you cannot hedge the same pair with offsetting positions. Many traders dislike FIFO, but it is a regulatory requirement, not a broker flaw.
One caution applies everywhere. SIPC does not cover forex accounts, so a regulated broker lowers your counterparty risk without removing it.
Regulation lowers the odds of losing your deposit to the broker. It does nothing about losing it to the market.
How to read a trust score
Many review sites publish a trust score, and the numbers vary widely between sites. Treat any score as a summary, not as proof. We weigh four factors, in this order:
- Regulator tier and register match. Forex.com scores high here.
- Parent company transparency. Also high, thanks to public filings.
- Withdrawal record. Complaints mostly concern verification delays, not refusals.
- Cost competitiveness. This is the weaker area, as the next section shows.
The verdict so far: Forex.com is safe in the sense that matters most. Your money sits with a supervised, well-capitalized firm. Whether it is the cheapest place to trade is a separate question.
How to Vet a Forex Broke Step by Step
Vetting a broker takes about 20 minutes, and the process is the same for any firm. Run the checks in order, because the first two can end your research early. If a broker fails on regulation, no pile of glowing reviews should change your mind.
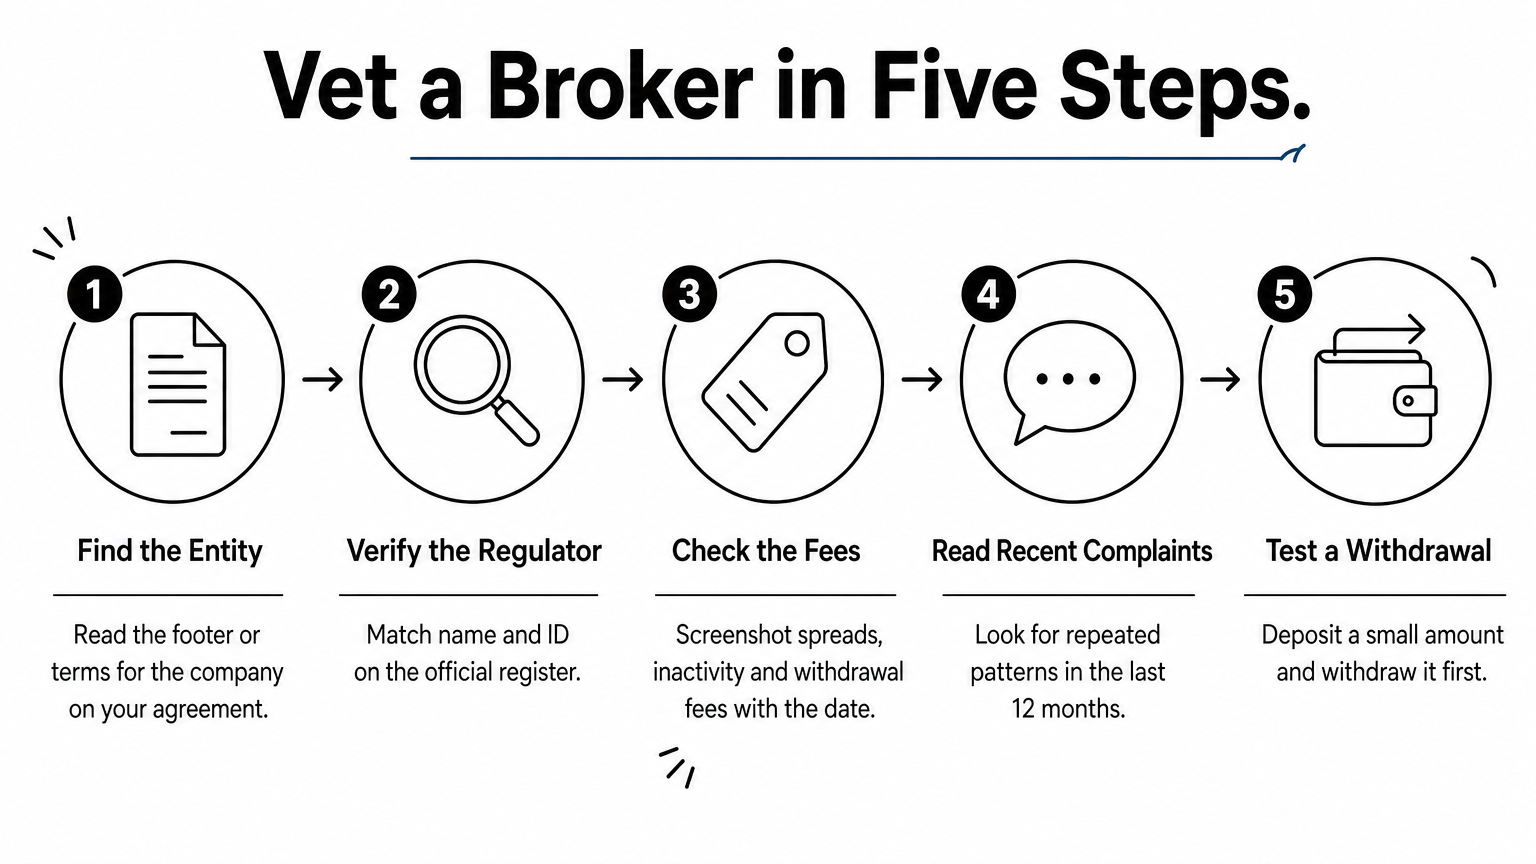
- Find the legal entity. Open the terms and conditions or the website footer. Write down the company name that signs your account agreement.
- Verify the regulator. Look that exact entity up on the regulator’s register. For U.S. firms, use NFA BASIC. Match the name and ID number, not just the brand.
- Check the fee schedule. Save the pages for spreads, commissions, inactivity fees and withdrawal fees. Screenshot them with the date.
- Read recent complaints. Focus on the last 12 months. Look for repeated patterns, such as withdrawal delays, rather than one-off rants.
- Test with a small deposit. Fund a small amount, place a few trades and withdraw it before you scale up.
Running the checklist on Forex.com
Step one has a catch for Forex.com. The brand operates through different legal entities in different countries, so a U.S. trader signs with a different company than a trader in the UK or Australia. Confirm which entity appears on your agreement, then check its status on the NFA register if you are in the U.S.
Steps three and five matter most after that. Compare the published spreads with what you see on the live platform, and note any inactivity fee. Then do the part most people skip: withdraw your test deposit and time it from request to arrival.
Keep a simple log with the date, amount, method and how long each step took. If support takes days to answer a basic question during a small test, expect slower service once you hold more money with them.
Forex.com Fees, Spreads and Account Types
How Forex.com charges you
Forex.com earns mainly from the spread, which is the gap between the buy and sell price. On its standard account, forex trades carry no separate commission because the cost is built into the quote. Many reviews quote one spread figure without saying which account or trading hour it came from, so treat such numbers with caution.
Spreads on major pairs such as EUR/USD are usually tight in calm markets. They tend to widen around news releases and at the daily rollover. Check live spreads on a demo account during the hours you actually trade, then compare them with two or three other brokers.
Account types at a glance
Available accounts depend on your country, so confirm what your entity offers. U.S. clients generally have fewer choices than clients in other regions.
| Account | Pricing model | Best for |
|---|---|---|
| Demo | Simulated, no real funds | Testing platforms and spreads |
| Standard (spread-only) | Cost sits in the spread, no commission | Beginners who want simple pricing |
| Commission (raw spread) | Tighter spread plus a per-trade commission, where offered | Active traders and scalpers |
The minimum deposit has historically been low, around $100 for many clients. Verify the current figure for your region and account before you fund anything.
Fees beyond the spread
The costs that surprise traders sit outside the quote. Pull each one from the official fee page and save it with the date.
| Cost | When it applies | What to check |
|---|---|---|
| Inactivity fee | After a long period without trading | The exact trigger and monthly amount |
| Overnight financing | Positions held past the 5 p.m. New York rollover | Whether the swap is a charge or a credit for your direction |
| Withdrawal costs | When you move money out | Broker fees, plus your bank or card provider’s fees |
| Currency conversion | When funding in a currency other than your account currency | The markup applied to the conversion |
Add these up for your trading style. A swing trader should care most about financing, while a casual trader who may step away for a year should watch inactivity charges. Compare total monthly cost rather than the headline spread, and the real price becomes clear.
Platforms, Tools and Education
Trading platforms
Forex.com offers a mix of proprietary and third-party software, and the lineup changes by region. Check which platforms your entity supports before judging the broker on its feature list.
| Platform | Best for | What to verify |
|---|---|---|
| Proprietary web platform | Browser trading with built-in charts | Order types and one-click trading |
| MetaTrader 4 and 5 | Expert advisors and automated strategies | Whether your region and account offer them |
| TradingView integration | Advanced charting and drawing tools | Whether you can place trades from the chart |
| Mobile app | Monitoring and managing open positions | Alerts, plus stop and limit editing |
Open a demo account and place the same order on web and mobile. Compare the fill price with the quote you saw, and note how fast the platform loads during a news release. Slow execution can cost you more than a small spread difference.
Research and education
Beyond execution, brokers typically supply market commentary, an economic calendar and technical analysis tools. These help you plan around events such as central bank decisions. Quality varies by region, so browse research pages while logged into a demo.
Education usually includes beginner guides, platform tutorials and webinars. Treat it as a bonus, not a reason to pick a broker. Good lessons explain position sizing and risk management, not just chart patterns. For a deeper look at this topic, see our guide to 7 forex risk management strategies beginners should use.
What Real Users Say About Forex.com
Feedback across Trustpilot, Reddit and app stores shows recurring themes more clearly than any single score. We did not run a survey, so treat this as a summary of common patterns, not as statistics. Check the latest posts yourself, because experiences change after platform updates.
What traders praise
- A long-established, regulated name, which matters most to U.S. clients with fewer safe options
- Polished web platforms and mobile apps
- Built-in charting, market commentary and an economic calendar
- A demo account for practice before funding
What traders complain about
Complaints are just as consistent, and most concern cost and service rather than missing money. Spreads, inactivity fees and slow support come up most often, followed by verification delays that slow withdrawals.
| Complaint | Likely cause | Your move |
|---|---|---|
| Wide spreads | Spread-only pricing, news hours | Compare live spreads on a demo |
| Inactivity fee | Long stretch without trading | Read the trigger, trade or withdraw |
| Slow support | Queues, region, verification | Test support during your trial |
| Withdrawal delays | ID checks, bank processing | Verify your identity early |
| Cannot hedge | NFA FIFO rule for U.S. clients | Adjust your strategy |
How to weigh the feedback
Sort every complaint into one of two buckets. A grievance about fees or rules is a pricing problem you can measure and avoid. A grievance about blocked or refused withdrawals is a safety problem, and one credible, documented case outweighs many complaints about spreads.
A fee complaint tells you the broker is expensive. A withdrawal complaint may tell you it is unsafe.
Check dates and details. Recent, specific posts that name an account type and a timeline are worth reading. Vague rants with no dates are noise.
How to Spot Fake Reviews and Forex Broke Red Flags
Signs a review is fake or paid
Fake feedback follows patterns. Watch for bursts of five-star posts within a few days, and for reviewers who have written only one post. Real users usually mention a detail, such as an account type, a withdrawal date or a platform problem.
- Identical phrasing across several reviews
- Praise that never mentions a fee, a platform or a withdrawal
- Company replies only to negative posts, asking you to move the chat to private messages
- Pages where nearly every link is a sign-up button
Paid reviews are harder to spot. Affiliate sites earn when you click, and that includes ours. Disclosure is the test. An honest page states the relationship and still lists real downsides.
Broker red flags that matter most
| Red flag | Why it matters |
|---|---|
| Guaranteed or “risk-free” profits | No legitimate broker can promise returns |
| Regulator named, but no license number | You cannot verify the claim |
| “Offer expires today” deposit pressure | Pushes you to skip your checks |
| A personal “account manager” on WhatsApp or Telegram | Common in boiler-room scams |
| Payment details naming a different company | The entity holding your money is unclear |
| Fees demanded before a withdrawal | Classic sign of a scam |
The last item deserves extra weight. No legitimate broker asks you to pay more money before it releases your own money. Taxes and fees are deducted from your balance, not charged as a new deposit.
If a broker asks you to deposit more before you can withdraw, stop and walk away.
What to do when something feels off
Stop funding the account first. Then search the exact company name alongside words such as “warning” or “complaint,” and compare the entity against the regulator’s register. For U.S. firms, that means the National Futures Association and its BASIC database. If the entity is missing from the register, treat that as your answer.
If you have already lost money, report it to the CFTC and keep every screenshot, receipt and chat log. Be wary of anyone offering to “recover” lost funds for an upfront fee. Recovery scams target people who have already been burned.
Who Forex.com Suits and How to Test It With Low Risk
Who it fits and who it doesn’t
Forex.com fits U.S. traders who value regulation and polished platforms over the lowest possible cost. It also suits beginners, because the demo account and education library let you learn before risking real money. Active traders who want a supervised, well-capitalized counterparty will find it a reasonable choice.
Look elsewhere if you chase high leverage, hedging or frequent promotions. U.S. rules cap leverage at 50:1 and enforce FIFO, and U.S. clients should expect fewer bonus offers than traders in other regions. If you trade from outside the U.S., check which entity and rules apply to you, because terms differ by country.
A four-week low-risk test
Treat your first month as an audit, not an investment. Keep the total small, for example $100 to $250, and use money you can afford to lose entirely. Log every step.
- Week 1, demo: Compare live spreads during your trading hours against two other brokers. Note platform speed on web and mobile.
- Week 2, funding: Finish identity verification and deposit the minimum. Record how long approval and funding take.
- Weeks 2 to 3, trading: Place small trades. Compare fills with the quotes you saw, and add up spreads, financing and conversion costs.
- Week 4, support: Ask a real question, such as how the inactivity fee is triggered. Time the reply and check whether it answers you.
- End of month, withdrawal: Request your full balance back. Record the speed, the fees and any extra document requests.
Score each step pass or fail. If the withdrawal is smooth and your costs match your estimate, raise your deposit gradually and keep watching the fee schedule. If any step fails, withdraw what remains and close the account before deciding whether the problem is the broker or your own setup.
Conclusion: Is Forex.com Legit?
Forex.com is legit. A publicly traded group owns it, and its U.S. entity is registered with the CFTC and is an NFA member. The real downsides concern cost and service, including spreads, inactivity fees and slow support. That makes it a solid fit for U.S. traders who value oversight over rock-bottom pricing.
The bigger lesson applies to every broker. Treat reviews as leads, not verdicts. Confirm the legal entity, check the regulator’s register, read the fee page and test a small withdrawal before you scale up. For more brokers judged on transparency and reliability, see our guide to the best forex brokers for transparency and reliability.
FAQ
Is Forex.com legit?
Forex.com is run by StoneX, a Nasdaq-listed group, and its U.S. entity is registered with the CFTC and is an NFA member. Legitimacy still depends on the specific entity on your account agreement, so confirm it on the regulator’s register.
Is Forex.com regulated in the U.S.?
The U.S. arm is registered with the CFTC and is a member of the NFA. You can look up the firm in the NFA’s BASIC database to check its registration status and disciplinary history.
What do traders complain about most with Forex.com?
The most common complaints are wide spreads, inactivity fees, slow support and withdrawal delays caused by verification. Complaints about lost funds are far less common in the reviews we looked at.
Does SIPC protect forex accounts?
No. SIPC does not cover forex accounts, so a regulated broker lowers your counterparty risk but does not remove it. Regulation never covers market losses.
How do I check whether a Forex Broke is regulated?
Find the exact legal entity on your account agreement, then search for that name and its ID number on the regulator’s register. For U.S. firms, use NFA BASIC. If the entity does not appear, treat that as a serious warning sign.